Protecting What You've Built
You've Built Something Worth Protecting. Let's Make Sure It Lasts.
A Clear Plan for Social Security timing, Medicare costs, and retirement income — so your money outlasts you.
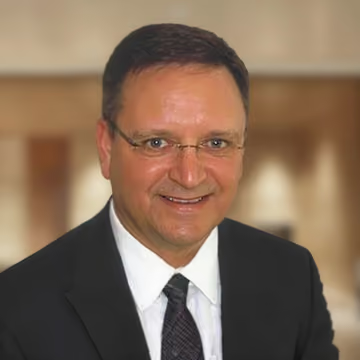
Richard Kirk
- Investment Advisor Representative
- CAPP™, RFC®, CSS™, NSSA™, IRMAACP™
"I've been doing this for over 20 years, and the question I hear most is some version of: am I going to be okay? People entering or already in retirement have worked their whole lives to get here. They're not looking for jargon. They want someone who will take the time to understand their situation, be straight with them, and guide them to a plan they can trust. That's what I do. We don't move any money until we've met multiple times and we both know the plan makes sense."
Certifications and affiliations shown above, see the disclosures page for what each one means and who issues it.
What's Keeping You Up at Night?
You've spent decades building toward retirement. You're close. But the closer you get, the louder these questions get. These are the three fears I hear most from people entering or in retirement.
Running Out of Money
What if you live to 90? What if healthcare costs more than you planned? What if the market drops right after you retire? These aren't abstract questions. They're the math problem every retirement plan has to solve. We build your income strategy around what you actually need.
Social Security and Medicare Surprises
Most people don't realize how much they can leave on the table by claiming Social Security at the wrong time. And Medicare is its own maze: Part A, Part B, Part D, IRMAA surcharges that can cost thousands a year if your income is too high. I'm NSSA and IRMAA certified. Getting these decisions right is what I specialize in.
A Bad Market at the Worst Possible Time
Losing 30% of your portfolio in year one of retirement hits differently than losing it at 45. You can't wait for a recovery when you're already drawing income. The market may come back, but the damage to your long-term plan can be permanent. The order of your withdrawals matters as much as the total.
Where We Take the Guesswork Out
Every person's situation is different. We don't walk in with a product to sell. We walk in with questions. We get to know your full picture first. Then we build a plan that actually fits where you are and where you're going.
Getting Social Security Right
When you claim matters more than most people realize. Claiming too early can cost you tens of thousands of dollars over a long retirement. We analyze your specific situation and build a claiming strategy around when it actually makes sense for you.
Navigating Medicare Without the Surprises
Part A, Part B, Part D, Medigap, IRMAA surcharges. It's a lot. I'm NSSA and IRMAA certified, which means this is an area I study and keep current on. We'll map out your Medicare options clearly so you can make a confident decision before your enrollment window closes.
Coordination Between the Two
Social Security and Medicare decisions interact with each other in ways that catch a lot of people off guard. We look at them together, not in isolation, so nothing slips through the cracks.
Income You Can't Outlive
The biggest fear in retirement is outliving your money. We use a three-bucket approach: a safe bucket for what you need now, a middle bucket for the medium term, and a growth bucket for the long haul. Each piece has a job. Together they give you stability without giving up on growth.
A Plan Built Around Your Number
We start by figuring out what your retirement actually costs. Not a generic estimate. Your number. Once we know that, we build income streams designed to cover it for as long as you live.
Protecting What You've Built
The solution to sequence of returns risk is structure. The safe bucket covers your near-term income so you're never forced to sell investments at the wrong time. The growth bucket stays invested and has room to recover. How you draw down matters as much as how much you have.
A Legal Standard, Not a Marketing Claim
I hold a Series 65 license and operate as a fee-based fiduciary for investment advisory services. That's a regulated standard with real legal teeth: I'm required by law to recommend what's in your best interest, and I don't earn a commission on the accounts I manage. When a recommendation is implemented through an insurance product like an annuity, the insurance company pays a commission out of its own revenue — never out of your account — and that's disclosed to you up front.
A Simple Four‑Step Process
We start with a 20–30 minute Introductory Call to confirm we're a good fit. Next, a Discovery Meeting covers your current situation and what you hope to achieve. Then we present a full plan, our recommendations and a proposal. If you decide to move forward, client onboarding usually takes 5–10 days. Three to six meetings before we move anything. You'll know exactly where things stand at every step, and you can walk away at any point.
20 Years. Clean Record.
I've been in this industry for over 20 years with no regulatory complaints or disciplinary actions. You can verify that on FINRA BrokerCheck. I bring that up not to brag, but because in this industry it actually matters.
Prospective Client Process
Four Steps to a Confident Retirement
Introductory Call
Expected Duration 20–30 minutes
Goals of Meeting
- Learn about your “why” for seeking our services
- Confirm we're a good fit
- Explain our process and what to expect
- Answer any questions you have for us
End Results
- If we both feel there could be value in working together, we'll schedule your next Discovery Meeting
- If either of us feels we aren't the best fit or the timing is not right, we'll thank you for the time
Discovery Meeting
Expected Duration 45 minutes to 1 hour
Goals of Meeting
- Learn about you, your current situation, and what you hope to achieve
- Discuss and align on responsibilities and next steps for a well‑managed process and successful outcome
End Results
- Schedule plan presentation and proposal meeting
Plan Presentation & Proposal
Expected Duration 45 minutes to 1 hour
Goals of Meeting
- Present a financial plan that aligns with your goals, equipped with recommendations to help you move forward
- Present a proposal for partnering to implement your plan and recommendations
End Results
- Take time to decide on our partnership
- We'll send a client service agreement and all partnership and account paperwork for e‑signature to get the process moving behind the scenes
Client Onboarding
Expected Duration 5–10 days (varies)
- Agreement/Packet Review
- Provide necessary information for setup
- Investment account recommendations & implementation
- Begin implementing financial strategy
- Transition to your client service calendar
Meet Richard & the AdvisorShare Wealth Management Team
Richard Kirk isn't alone in this. LifeGuard Retirement Planning partners with the elite team at AdvisorShare Wealth Management to make sure you get the full picture, and full support in all areas.
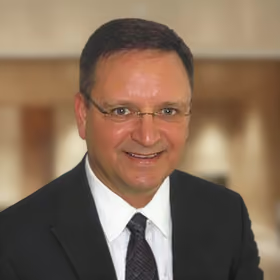
Richard Kirk
Investment Advisor Representative
Read Bio
Blair Schadler, CAPP™
Case Design Specialist
Read Bio
Joseph Maas, CFA
Investment Management Specialist
Read Bio
Roccy M. DeFrancesco, Jr., JD, CAPP, CMP, CRCS
Attorney and Asset Protection Authority
Read Bio
Jonathan Camarda, CFA
Investment Design Specialist
Read Bio
Daniel McDonald
Annuity & Insurance Specialist
Read Bio

Real Client Outcomes
Protecting Principal Through a Market Crash
A client inherited an IRA that was invested in mutual funds and told us plainly: she didn't want to lose money. We moved it into a fixed index annuity. Over the next year and a half, the S&P 500 fell about 57% during the 2008 financial crisis (October 2007 to March 2009) — her account didn't lose a dime.
Anonymized examples from clients we've worked with. Every situation is different — these aren't a guarantee that any other client will see similar results.
Common Questions
Six questions I hear most often. For everything else — Medicare, Roth conversions, asset protection, estate planning, and more — the full FAQ has answers organized by topic.
Is Richard a fiduciary?
For investment advisory services, yes. I hold a Series 65 license, and by law I'm required to recommend what's actually in your best interest, not whatever pays the biggest commission. That's a legal standard, not a marketing slogan. I'm a fee-based fiduciary financial advisor, and I don't earn a commission on the accounts I manage.
Read the full compensation disclosure →What happens if the market drops right after I retire?
This is one of the biggest risks in retirement income planning, and it's different from the risk you took while you were still working. Losing a large chunk of your portfolio in year one of retirement hits differently than losing it at 45, because you can't wait it out while you're also drawing income from it. That's why I build income around a bucket approach: money you need soon stays safe, and money you don't need for years stays invested with time to recover.
See how principal-protected tools fit in →Should I convert my traditional IRA to a Roth?
It depends on more variables than a rule of thumb can capture, mainly whether you expect a higher or lower tax bracket in retirement, and whether you'd pay the conversion tax from the IRA itself or from other funds. As a general starting point, a Roth conversion tends to make less sense if you'll be in the same or lower bracket later, and more sense if you expect a higher one. I run the actual numbers for your specific situation instead of guessing.
Read the full Roth conversion breakdown →When can I actually talk to you about Medicare?
Medicare's Annual Enrollment Period opens every October 15, but as a Medicare-qualified agent, I'm available for Medicare planning guidance year-round. Medicare Supplement (Medigap) coverage specifically can be reviewed or enrolled in at any time of year, not just during Annual Enrollment.
See what I offer →How do I get started?
Call, email, send a message through the contact form, or book an Introductory Call directly, whichever is easiest for you. There's no cost and no obligation to that first conversation. Some people come in with one specific question, others want to walk through their whole situation. Either way is a fine place to start.
Get in touch →Is there a cost or obligation for a first conversation?
No. The first conversation, and tools like the Risk Analyzer, are offered as free, no-obligation starting points, so you can see where you actually stand before deciding whether to move forward with anything.
Schedule a Call →I don't offer every Medicare plan available in your area. For a full list of every plan and every carrier, visit Medicare.gov or call 1-800-MEDICARE (1-800-633-4227).
Top 5 Roth IRA Conversion Mistakes
How to Reduce Taxes in Retirement
For decades, savers were told the same story: contribute pre-tax now, and you'll be in a lower bracket when you retire. For many retirees, it hasn't worked out that way — Required Minimum Distributions and shifting tax rates can quietly erode a lifetime of savings. This free guide breaks down the five most common Roth conversion mistakes and the strategies that put more of what you've earned back in your pocket.